
Seventy Years of Housing Growth in Orange County, California
By Rick Tobin
Few places in the world have seen homes appreciate in value over the past 70 years as Orange County, California. For example, the nominal median home price in Orange County increased by somewhere between 6,000% and 7,900% between 1956 and 2026, as per sources like Zillow.
By mid-2026, the median home value for Orange County homes was in the $1.22 to $1.41 million price range, according to sources like Redfin.
It’s been said that the three most important factors related to home value trends are tied to “location, location, and location.” There are few places more beautiful in the world than the incredibly scenic Orange County region where I grew up and lived for most of my life.
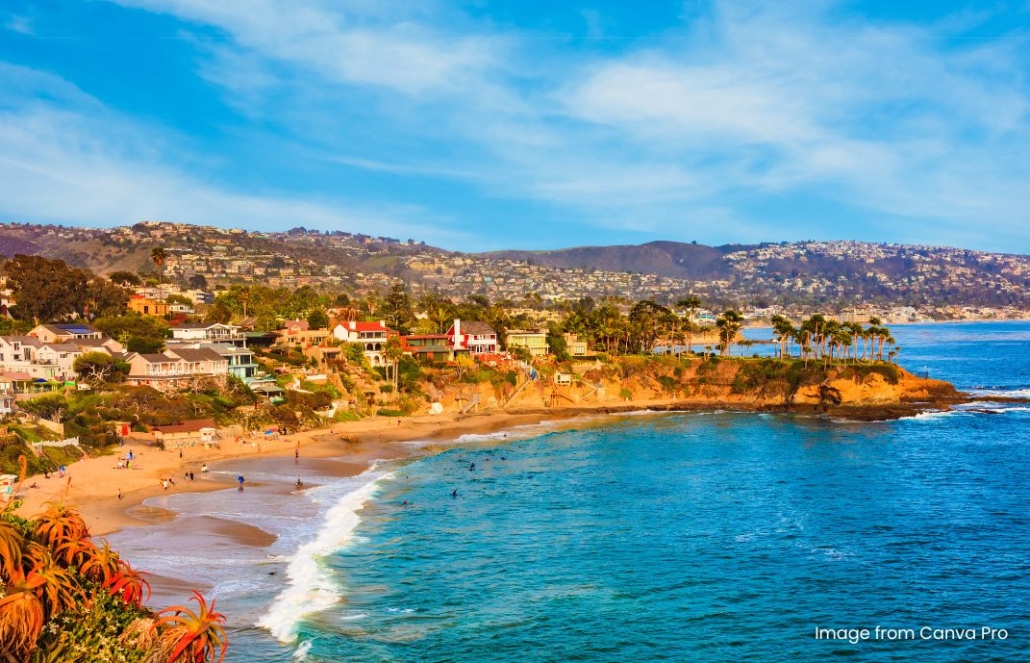
The closer that a city is to the Pacific Ocean, the higher the property value. The six cities in Orange County that are located adjacent to the Pacific Ocean are as follows from north to south: Seal Beach, Huntington Beach, Newport Beach, Laguna Beach, Dana Point, and San Clemente.
The three most populous cities in Orange County are Anaheim, Santa Ana, and Irvine, with each city having a population surpassing 300,000.
The combined land and water area for Orange County is listed as being 948 square miles. Of those total 948 square miles, 799 square miles are on land, while 157 square miles are water (lakes, rivers, etc.).
The most densely-populated metropolitan area in the U.S. is the Los Angeles-Long Beach-Anaheim region, with almost 7,500 people per square mile, as per the US Census and Wikipedia.
article continues after advertisement
The Origins and Evolution of Orange County
1956: A newer suburban home in Orange County was priced as low as $15,000 to $20,000, partly depending on the proximity to the nearby Pacific Ocean coastal region. The opening of Disneyland in Anaheim one year earlier in 1955 shifted this local economy to a more global economy.
There were approximately 490,000 residents who lived in Orange County back in 1956. Farmland regions filled with orange groves (hence the Orange County name origins) began to turn more into suburban neighborhoods. Garden Grove, Costa Mesa, Anaheim, and other regions later were incorporated as cities and rapidly expanded over the next fifty years.
1970: Median county home prices were roughly $30,000, which was about three times the median household income at the time.

1980: Orange County home prices varied between $95,000 and $110,000, according to sources like the Los Angeles Times. Starting in this 1980 year near interest rate peaks, such as the US Prime Rate reaching 21.5% in December 1980, California’s statewide home prices started to decouple from the national average and rise at a much faster pace.
1990: Homes reached almost a $230,000 value range in Orange County during this late 1980s and early 1990s home price boom before later starting to fall in value in the mid-1990s. Southern California was especially hit hard by falling home values in the early to mid-1990s as the Savings and Loan Crisis worsened across the nation.
2000: Orange County homes reached the $240,000 to $260,000 pre-bubble baseline before later exploding in value, due to massive rate cuts by the Federal Reserve drove short-term rates down to almost zero for several years, while the 10-year Treasury yield and corresponding 30-year fixed mortgage rates also fell at a rapid pace.
2010: Following the massive housing crash that hit California especially hard with a statewide percentage loss average of -41.7% between peak 2007 and 2012 or 2013, Orange County home prices settled back down in the $450,000 to $500,000 price range.
2020: After several years of record low mortgage rates, home prices in Orange County were in the $790,000 to $950,000 range, as per sources like the Los Angeles Almanac.
2026: Fifty years later here in 2026, there are almost 3.2 million residents in Orange County. Median home prices also reach the $1.2 to $1.4 million price range.
Many prime oceanfront or beachfront coastal homes in Huntington Harbour, Newport Beach, and Laguna Beach can vary from $3 million up to $110+ million. For example, a cliffside mansion in Laguna Beach’s incredibly beautiful Emerald Bay community sold for the highest price ever in Orange County at a staggering $110 million dollar sales price.
Top 10 Employers by Workforce Size in Orange County

The median household income in Orange County in 2026 surpassed $116,000, as per the US Census Bureau. Just over 50 years earlier in 1955 when the US Census kept national records, the median household income was listed at $4,400 per year.
1. The Walt Disney Company Company – 34,000 employees
2. University of California, Irvine (UCI) – 26,000 employees
3. Providence South Division – 25,000 employees
4. Kaiser Permanente
5. Allied Universal – 7,200 employees
6. MemorialCare – 6,700 employees
7. Boeing Company
8. First American Financial Corporation
9. The Irvine Company
10. Edwards Lifesciences
Sources: Orange County Business Council and Orange County Business Journal
Orange County Spotlight City: Huntington Beach
Now, let’s focus on my hometown of Huntington Beach (aka “Surf City, US”) where I lived for much of my life.
1950s to 1970s (Post-War Housing Boom): The late 1950s marked the beginning of the shift from larger urban regions like downtown Los Angeles to newer suburban family-friendly communities such as those found in areas like beautiful Huntington Beach. In 1956, the population there was about 6,000 to 8,000 people.
The median home prices fluctuated between $12,000 and $18,000 back in 1956. New home development there peaked in 1973 as neighborhoods began to rise up out of once empty fields. Popular architectural styles in Huntington Beach were mid-century modern ranches and single-story homes with open carports, low-pitched roofs, and larger outdoor yards and living spaces.
By the late 1970s, home values for tract homes were priced between $40,000 and $60,000.
1980s to 1990s (Custom Homes and Master-Planning Designs): Fancier developments began to increase in my old Huntington Harbour neighborhood. Later, larger master-planned communities near downtown Huntington Beach, such as the SeaCliff Golf Course community, became quite popular as home prices really began to rapidly rise in both locations.
2000s to 2010s (Great Recession, Bust, and Rebound): Home values in Huntington Beach hit the $825,000 price range in early 2007, according to the Orange County Register. By Q4 of 2007 near the previous housing bubble peak, median home prices reached $875,000 to $879,000.
After the housing bubble popped (2008 to 2012), median home prices in Huntington Beach fell to between $475,000 and $635,000, according to DataQuick.
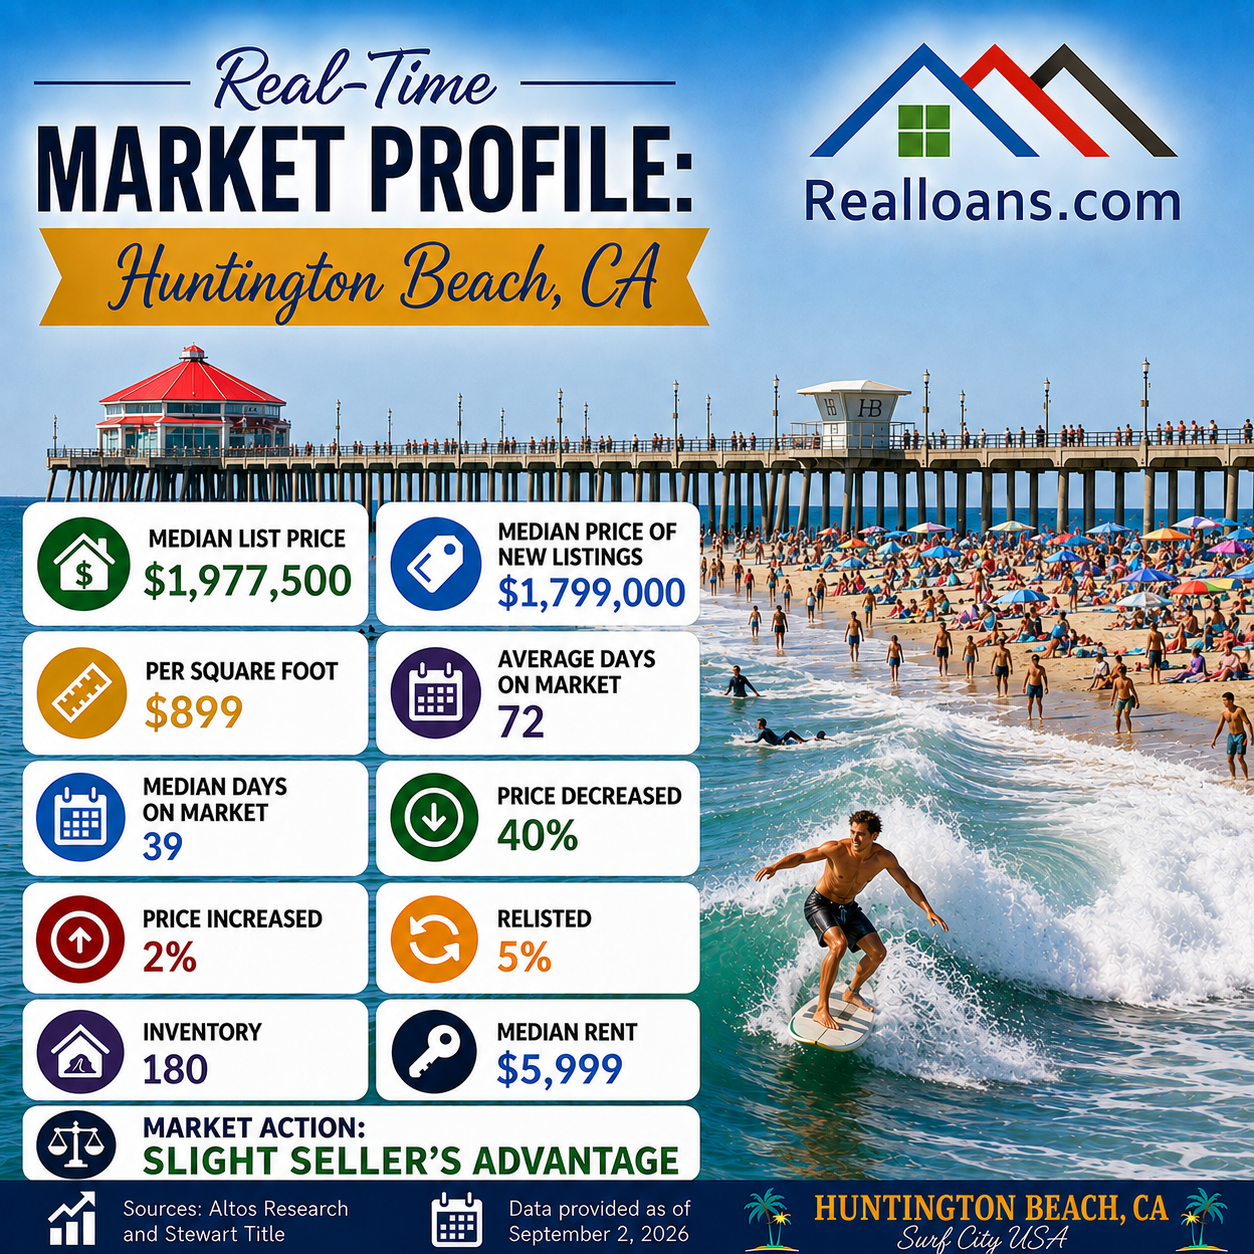
2026: The population of Huntington Beach as of this year is closer to 190,000 people. As of September 2, 2026, the most recent home value trends are as follows in my digital post created below:
Orange County, CA: The Epitome of Suburbia
Suburbia’s Evolution: The 1950s
The decade of the 1950s began with a desire by many Americans to achieve the ideal lifestyle of suburban home ownership with a white picket fence and all, as I shared in past articles about the evolution of suburbia.
Many Americans were still saddened by the devastation of fighting wars in the 1940s. The threat of the possible Korean War also caused concerns and stress in the 1950s. In addition, the fear of nuclear warfare caused many Americans to seek peace and safety within the comforts of their new suburban homes.
Easier Credit Access and Better Commuting Options
The increased availability of credit from banks, thrift and loans, and other lenders helped suburbia grow in the 1950s. The introduction of credit cards (or “charge plates”) began in February of 1950 by a man named Frank X. McNamara. He ran a small New York loan company. Mr. McNamara came up with the novel idea of offering a single credit card to many different people.
His credit card/charge plate was named “The Diners Club” card. The card was later accepted at department stores, restaurants, and a few hotels. American Express and Carte Blanche soon acquired Diners Club, and the expansion of consumer credit took off from there.

The introduction of credit cards helped restaurants and small businesses increase their sales tremendously in the 1950s. With the ready supply of new credit, Americans began visiting more restaurants, traveling, and spending money at shopping malls (first opened in 1956).
The 1956 year was the same year when President Dwight D. Eisenhower helped push through the approval of the Interstate Highway Act. The new bill funded the construction of over 46,000 miles of new roads, with more than $130 billion of federal money. The new roads helped car, truck, and suburban home sales increase dramatically throughout the nation.
McDonald’s, Disneyland, and Hollywood
The 1950s was also the decade that gave us the introduction of the national franchised business. Ray Kroc, a successful milk shake mixer salesman, was impressed with his customers’ The McDonald Brothers Self Service Restaurant in San Bernardino, California. Ray Kroc was amazed by the efficiency of their automated food serving system as well as with the high number of food sales at their restaurant. Mr. Kroc made an agreement with McDonald’s to franchise their restaurant business nationwide.
Hollywood began to get in on the act of promoting the perfect American lifestyles with hit television shows like Father Knows Best, Leave It To Beaver, and Ozzie and Harriet. As more and more television viewers watched these television shows, more Americans tried to emulate these shows by moving out to suburbia to find their own version of the “white picket fence” home.
Walt Disney purchased 160 acres of orange groves in Anaheim in the early 1950s, and began the construction of the ideal place to visit – Disneyland. Television, movies, and theme parks began to focus on entertaining people as a way to distract them from the daily pressures of life.
As shared earlier, Anaheim is currently the most populous city in Orange County with more than 340,000 residents. Disneyland also continues to be the #1 largest workforce employer in Orange County.
article continues after advertisement
From Levittown to Orange County
The high fertility rates after World War II helped fuel the suburban housing boom as larger families needed larger suburban homes. America’s fertility rate peaked at 3.77 children per married household in 1957. The suburban location provided them with a home, garden, car, and the model American family lifestyle as seen on television.
The overall U.S. suburban population increased from almost 27 percent in 1950 to anywhere between 55% and 65% today, according to Pew Research.
Homeownership rates increased from 43 percent in 1940 to about 65% in 2026. The increased number of home mortgages, credit cards, roads, freeways, jobs, the size of families, and the overall U.S. population all led to the demand for more suburban communities around the nation.
Suburban communities began in the northeast with places like Levittown, NY and Allentown, PA. Franchised businesses, theme parks, movies and television shows, which glorified the suburban lifestyle, began or were created in Southern California.
As the 1950s progressed, these suburban regions had significant impacts on other regions throughout America. More cities and states began to take on the look of the best of the lifestyles first seen in Orange County.
The 1950s should be looked at as the decade that helped form the modern prosperous American society. Americans in the 1950s experienced the Korean War, the expansion of franchised businesses, the evolution of television, movies, theme parks, rock and roll music, rebelling teenage youth, and the space race with the other “Superpower” in the world – the Soviet Union.
Suburbia in the 1950s offered people the American Dream as well as a sanctuary from the daily pressures of life. Suburbia’s roots really began in the 1950s, and would continue to evolve over the next 70 years.
Since the 1950s, more and more regions across the nation and world have tried to duplicate the suburban family lifestyle that was first perfected in Orange County. Yet, they’re not as fortunate to have the beautiful scenery and incredible weather throughout the year. This is partly why demand for real estate in the prime Orange County location should continue to outperform other regions across the nation.

Rick Tobin has worked in the real estate, financial, investment, and writing fields for the past 30+ years. He’s held eight (8) different real estate, securities, and mortgage brokerage licenses to date and is a graduate of the University of Southern California.
Rick provides creative residential and commercial mortgage solutions for clients across the nation. He’s also written college textbooks and real estate licensing courses in most states for the two largest real estate publishers in the nation; the oldest real estate school in California; and the first online real estate school in California.
Please visit his website at Realloans.com for financing options, join his investment group at So-Cal Real Estate Investors, and follow his new So-Cal Real Estate TV channel for more details.
Rick Tobin
Realloans (Real Estate Loans)
https://realloans.com/
Phone or Text: (760) 485 – 2422
NMLS 1934868
Equal Housing Opportunity / Equal Housing Lender
To quickly apply online: Loan Application
For our real estate course: Learn Real Estate
Please follow our new real estate channel (watch on television, computers, and phones): So-Cal Real Estate TV
Our Facebook business pages: Realloans, Inside Los Angeles, Inside Pacific Palisades, Inside Long Beach, Inside Huntington Beach, Inside Orange County, Inside La Jolla, Inside San Diego, Inside Lake Elsinore, Inside Temecula Valley, Inside Coachella Valley, and So-Cal Real Estate Investors.
Here are some of my articles: The Fall of 2025 and Rise of New Opportunities, The Intersection of Declining Home Sales and Creative Marketing, Are Lower Rates on the Horizon?, Weather Extremes, Homes, and Insurance Risks, The California Gold Rush Boom, and Are You Focused on Commercial Real Estate?
Please join my So-Cal Real Estate Investors group that meets at Canyon Lake Golf & Country Club, Shoreline Yacht Club in Long Beach, and online: So-Cal Real Estate Investors.