For 36+ years, she’s guided 6,000+ families, safeguarding over $2.5 Billion—and not a single client has lost a dime due to market downturns.
Kris Miller is the author of the #1 bestselling book, “Ready for PREtirement: 3 Secrets to Safe Money and a Fabulous Future.” She’s the founder of Healthy Money Happy Life and she teaches hard-working people like us how to protect our money and ensure that we’ll have enough to live well even if we choose to retire. The secrets she has to share are rarely discussed outside the 1%. But you don’t have to be a billionaire… yet, to take advantage of what Kris is going to share with us today.
Her promise is practical and transformative: create income you can never outlive, align money with purpose, and live your legacy now—no matter the market.
Proof: 6,000+ families protected • $2.5 Billion safeguarded • Not a single client has lost a dime due to market downturns.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/retirement.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-23 02:18:572026-07-31 01:34:09Create Income You Will Never Outlive — Key Insight on Retirement Planning
Many borrowers think credit scores measure income. They do not.
Others assume they measure wealth. They do not.
Credit scores measure what lenders care about most: whether you are likely to repay obligations exactly as agreed.
A credit score is not a judgment of character. It is a risk model.
Higher scores signal lower perceived default risk. Lower scores create friction: higher pricing, more documentation, stricter conditions, and more denials.
“Credit scores do not measure success. They measure repayment behavior.”
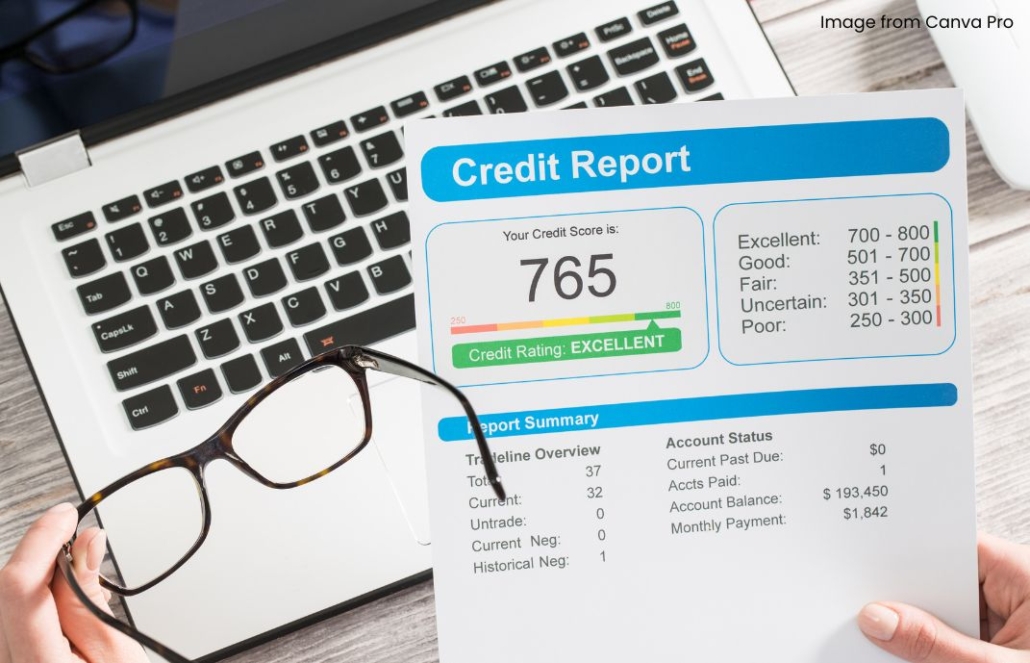
A FICO score generally ranges from 300 to 850 and reflects five major categories of credit behavior. Payment History and debt utilization carry the most weight, together representing roughly 65% of the score. [FICO Scores | Word], [myfico.com]
Credit Scores Determine the Cost of Capital
The gap between a 580 score and an 800 score can mean tens of thousands of dollars in extra borrowing costs.
article continues after advertisement
Stronger scores commonly produce:
· Lower mortgage rates
· Better credit card terms
· Quicker loan approvals
· Higher credit limits
· Lower required deposits
· Stronger rental qualification odds
Low scores usually lead to the opposite outcome.
Borrowers with stronger scores typically secure capital faster, at lower cost, and with fewer restrictions.
“Poor credit shows its real price when capital is needed most.”
Credit Score Ranges in Practical Terms
Score Range
Risk Assessment
Common Lending Result
800–850
Exceptional
Best pricing and terms
740–799
Very Good
High likelihood of approval
670–739
Good
Usually financeable
580–669
Fair
Higher pricing and tighter underwriting
300–579
Poor
Higher denial risk and discounted terms
These ranges are guides, not guarantees.
Final pricing still depends on the lender, loan type, collateral quality, and full credit profile.
“Approval is binary. Pricing is where credit scores extract the real cost.”
The Five Metrics Driving Your Credit Score
1. Payment History (35% of FICO): The Trust Record
Payment History is the largest factor in a FICO score. It shows whether obligations were paid as agreed. [myfico.com], [FICO Scores | Word]
Lenders start with one question:
Did you pay others on time?
Scoring models examine:
Core Payment-History Metrics
· Count of late payments
· Depth of each delinquency
· How recently delinquencies occurred
· Pattern of missed payments
· Collection activity
· Charged-off accounts
Foreclosures
Bankruptcies
A recent 90-day delinquency hurts far more than an old, isolated late payment.
Scoring models do more than count errors.
They detect patterns.
“Credit scores preserve the record of promises kept—and promises broken.”
What Borrowers Often Overlook
Many borrowers assume that paying eventually is sufficient.
Credit scoring does not work that way.
The gap between 29 and 30 days late can matter because many creditors report delinquencies only after the 30-day threshold.
Payment timing matters.
2. Amounts Owed and Credit Utilization (30% of FICO): The Leverage Test
Payment History shows whether you pay on time.
Utilization shows how heavily you rely on available credit.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/credit-score.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-22 04:58:352026-07-23 03:12:30Credit Scores: The Five Metrics That Determine Whether Capital Moves Toward You—or Away
Former sales leader at LSO Parcel, GLS US, and TForce Logistics to drive national growth strategy and customer expansion
(July 8, 2026) — Hovership, a technology-infused regional delivery provider serving more than 25 states, today announced the appointment of Mike Maya as Senior Vice President of National Sales. Maya brings nearly two decades of experience leading enterprise sales, strategic partnerships, and national account growth across the parcel and logistics industry, positioning Hovership for its next phase of expansion.
As Senior Vice President of National Sales, Maya will lead Hovership’s national sales organization, customer acquisition strategy, and strategic partnerships while accelerating revenue growth among retailers, e-commerce companies, and enterprise shippers seeking a scalable, lower-cost alternative to traditional national carriers.
“Mike understands where the logistics industry is headed and what customers expect from a modern delivery partner,” said John Zendejas, Founder and CEO of Hovership. “His deep experience building relationships with enterprise shippers and delivering growth across some of the industry’s leading regional carriers makes him the ideal person to lead our national sales strategy. As we continue expanding our footprint and technology capabilities, Mike will play a critical role in helping more businesses rethink what’s possible with regional delivery.”
article continues after advertisement
Maya joins Hovership after serving as Vice President of Sales at LSO Parcel, where he led strategic sales initiatives across the company’s regional delivery network. Prior to LSO, he held leadership roles at GLS US as Senior Director of Partnerships & Solutions and Director of National Accounts, where he focused on enterprise customer growth, strategic partnerships, and national account development. His career also includes sales leadership positions with GLS, TForce Logistics, Golden State Overnight (GSO), and Norco Delivery Service, building a reputation for developing long-term customer relationships and driving sustained business growth across the regional parcel market.
“What attracted me to Hovership is its vision for the future of logistics,” said Maya. “Most carriers compete on price and capacity. Hovership leads with transparency, technology, and a proactive customer experience. We’re giving shippers the data, visibility, and operational insights they need to make better business decisions while providing a regional delivery network that delivers exceptional performance, greater control, and meaningful cost savings.”
Hovership combines multi-state regional delivery coverage with modern AI and automation to deliver enhanced shipment visibility, real-time driver tracking, proactive recipient communications, and operational transparency. The company’s technology-infused approach helps retailers, e-commerce companies, and enterprise shippers improve delivery performance while reducing transportation costs.
In his new role, Maya’s immediate priorities include expanding Hovership’s enterprise customer base, strengthening strategic partnerships, and supporting the company’s continued geographic growth.
Hovership serves the country’s most important shipping markets with extensive ZIP code and population coverage throughout Texas, California, Florida, and beyond. The network includes all four major Texas metropolitan areas—Dallas-Fort Worth, Houston, Austin, and San Antonio—allowing businesses to reach more customers through a single regional carrier.
About Hovership
Hovership is a technology-infused regional delivery provider serving more than 25 states, giving shippers a scalable, lower-cost alternative to national carriers. The company combines expansive regional coverage with AI-powered operational tools, real-time shipment visibility, and performance-driven logistics solutions to help retailers, e-commerce businesses, and enterprise shippers improve efficiency, reduce transportation costs, and enhance the delivery experience.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/logistics-1.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-21 06:31:502026-07-21 06:32:28Hovership Appoints Logistics Industry Veteran Mike Maya as Senior Vice President of National Sales
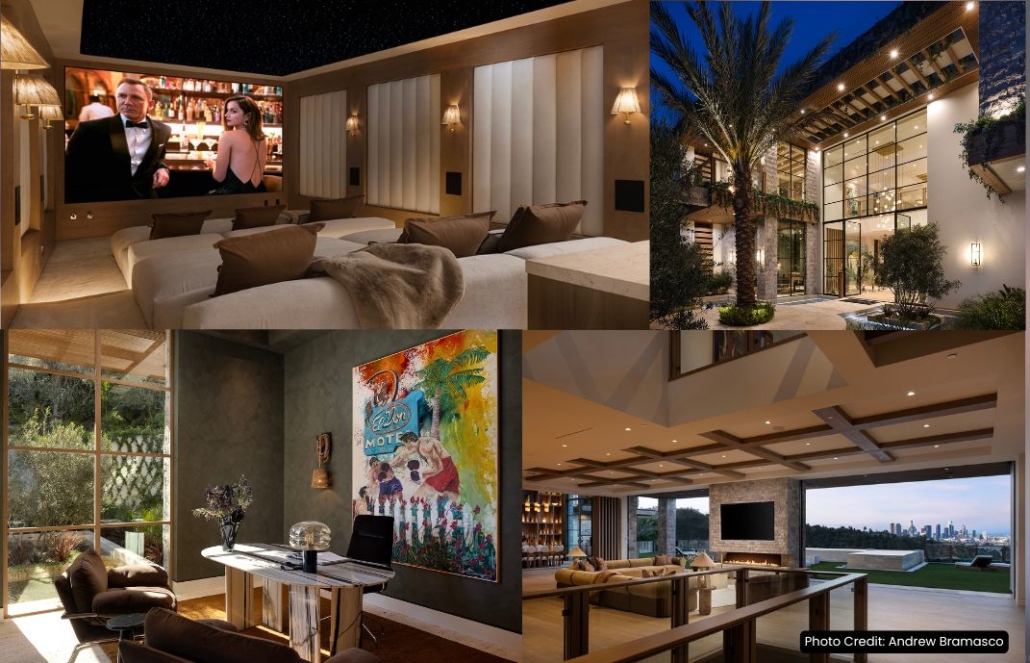
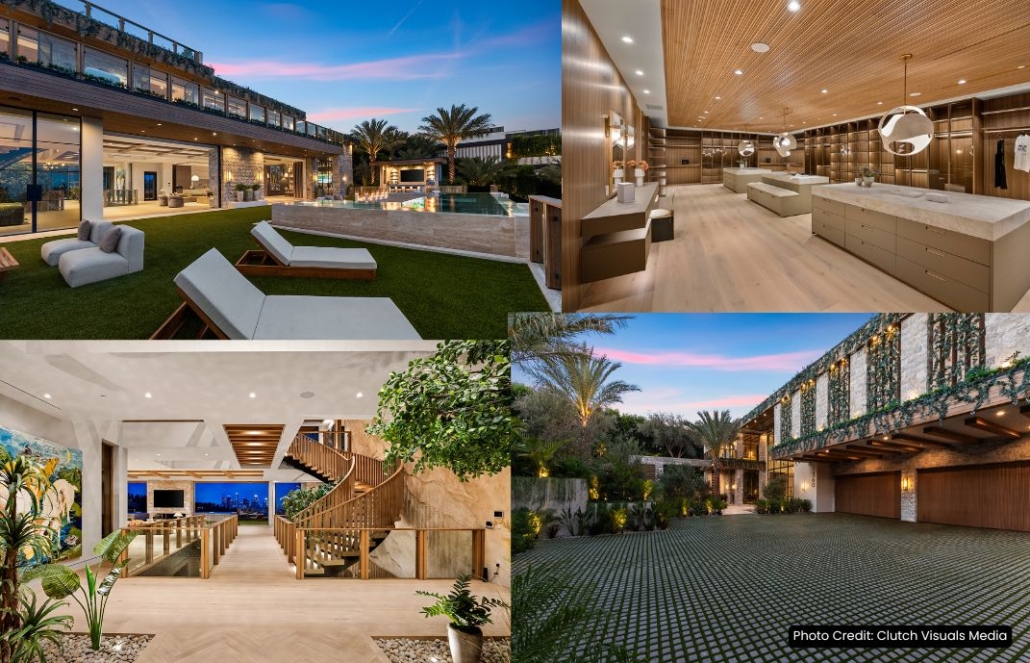
Developer to the stars, Ramtin “Ray” Nosrati, was born in Iran and moved to the United States as a child. Attributing his talents for home building and design, he credits his parents’ Sunday drives exploring Los Angeles area open houses and his childhood LEGO collection for sparking his early interest in the business. Ray began his career in the cell phone business, a success that he sold in 2002, using the profits to jump into real estate. Beginning with some chicken ranches, he used the land to build tract homes for middle-class buyers. Following his dream, he then began buying “tear-downs” in the Los Angeles area to build more expensive custom homes. Ray parlayed that success to the top of the home-building business and became the go-to builder for celebrities and rich clients in LA’s most upscale neighborhoods.
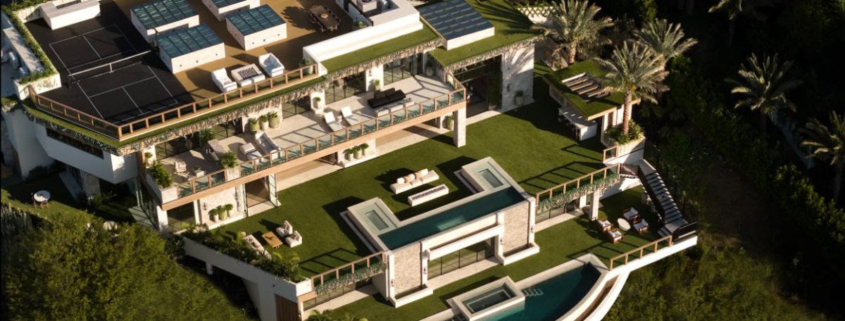
Ray’s newest showpiece home is Opal, a spectacular Beverly Hills chateau, for $53 million. Opal combines contemporary architecture with resort-style amenities across multiple levels. The palatial home spans 19,100 square feet and includes custom European furnishings. Opal’s interiors feature expansive glass walls with gorgeous views of downtown LA and the Pacific Ocean, a double-height foyer, a two-story dining room with skylights, and a travertine-clad kitchen with custom appliances, an oversized island, and a separate catering kitchen with a commercial-grade walk-in refrigerator. A glass elevator connects all four floors.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/house.jpg6741200dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-21 05:15:562026-07-21 05:17:34Developer to the Stars Uses ‘WOW’ Factor to Market $53 Million Home
Network with Investors from Across the Nation… ONLINE today.
Investors, be sure to attend this week’s virtual Dealmaker’s and Financial Tactics Meetup. This timely and informative online session is moderated by Michael Morrongielo from BAWB – Bay Area Wealth Builders.
Join us to discuss the latest real estate news, plus we are here to assist with any questions or concerns you may have. Be sure to register for this Special Virtual Meeting.
What You’ll Learn Today:
* Listen to Real-Life REI Deal Examples * Learn from Investment Mistakes & Triumphs * Our Investing Pro will Listen to Your Deals * Network Online with Other Investors * This in an Interactive Session for All * Our Goal to Assist, Encourage, Educate
Michael Morrongiello is an active investor who specializes in Real Estate & Real Estate “Paper” investments. Widely known as having one of the most knowledgeable & creative minds in the paper business, Michael started creating paper as a result of his own Real Estate investment activities in the early 1980’s. He is very active in the Buy/Sell renovation business of properties in the San Francisco Bay Area.
Michael is the author of Paper into Cash – The Convertible Currency-the definitive home study course that assists you in structuring seller financed transactions while creating marketable Notes and The Unity of Real Estate and “paper” – a course book that outlines numerous real world in the marketplace transaction scenarios and solutions where Real Estate and financing techniques involving “paper” can be effectively used.
Michael is also the program director for BAWB- the Bay Area Wealth Builders Association- an educational support group for both the beginning and seasoned real estate investors.
RSVP to Our In-Person Summit!
Network with Hundreds of Real Estate Investors!
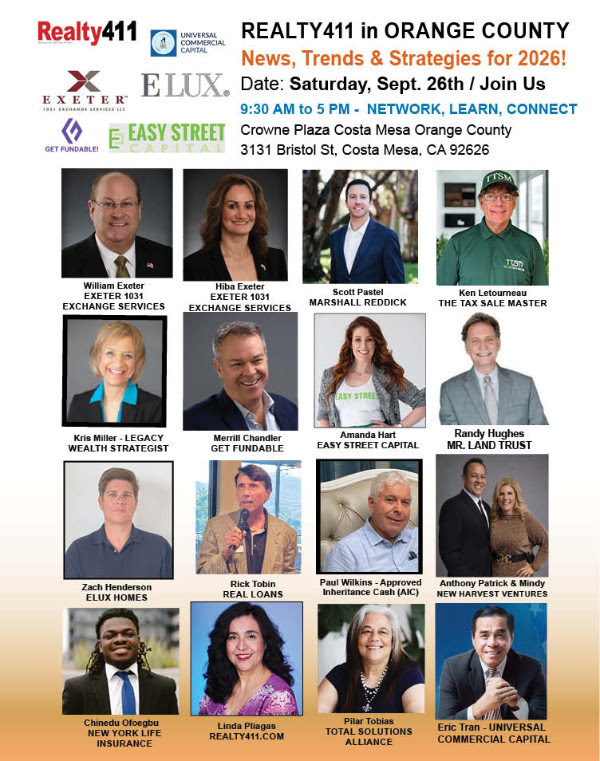
Hello friends, be sure to join us for our FREE Realty411 Expo in Costa Mesa on Saturday, September 26th, 2026 — We have new educators and familiar friends joining us. Hundreds of investors in our network have already registered!!!
This one-day impactful conference is designed to help guests achieve success in real estate investing and beyond.
Be sure to attend this complimentary event featuring timely REI insight, top educators, and active investors from locally and out of state. Friends, join us early for best seating and networking.
Parking and admission are FREE.
Real estate investors, agents/brokers, private lenders, entrepreneurs, property managers, wealth builders and business owners… this event is designed just for YOU.
“Realty411’s News, Trends & Strategies Summit” is being held at: CROWNE PLAZA COSTA MESA ORANGE COUNTY, 3131 Bristol St, Costa Mesa, CA 92626. The venue is located near John Wayne Airport.
If you are serious about personal finance, join us to learn about top markets, success strategies, insider tips, and so much more. The latest edition of Realty411 magazine will be available, as well as past editions, too.
SELF PARKING FOR THIS EVENT IS FREE ONSITE- Plus, there is plenty of space for overflow parking available nearby.
DON’T MISS THIS SPECIAL EVENT IN SOUTHERN CALIFORNIA.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/deal.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-21 02:48:172026-07-24 00:26:54DealMaker’s & Financial Tactics Forum
Defined by tight delivery windows, 24/7 operations, and increasingly sophisticated tenant demands, zoning due diligence has become one of the most consequential components of a successful acquisition or development of an industrial or logistics property. Yet it remains among the most underestimated.
Stakeholders often assume that if a property “looks industrial,” zoning will support industrial operations. As many buyers and lenders discover the hard way, this assumption can derail closings, delay occupancy, and expose owners and tenants to long-term operational and financial risks.
“Industrial assets tend to look deceptively simple,” said Alan Hall, vice president of Zoning Solutions at LightBox. “But zoning determines whether a facility can actually operate as intended, expand over time, or even survive a tenant change. That risk is easy to overlook until it’s too late.”
article continues after advertisement
Industrial and logistics properties carry unique zoning hazards that differ materially from typical commercial assets. Heavy truck circulation, outdoor storage requirements, specialized operating hours, and rapidly evolving design standards all collide with local zoning codes that were often drafted decades ago with vastly different industrial profiles in mind. This mismatch creates fertile ground for surprises, many of which can only be identified through meticulous, expert zoning analysis.
“Industrial assets are attractive because the economic value proposition feels straightforward,” said Carl Groner of Palisades Property Trust. “But the zoning issues tied to use, access, and entitlement are often far more complex than they appear. What looks like a simple box can contain constraints that limit current operations or eliminate future value-added potential.”
The risks become most apparent in a handful of recurring scenarios. Below are two of the most common and consequential zoning pitfalls, along with examples of how they can derail a transaction or impair an asset’s long-term performance.
Non-Conforming Use: The Silent Deal-Killer
Among the zoning risks that catch industrial buyers off guard, non-conforming use is both the most common and the most dangerous, often hiding behind years of uninterrupted operations and assumed compliance.
A surprising number of warehouses, manufacturing plants, and logistics hubs operate legally only because they pre-date current zoning regulations. These uses may be “grandfathered,” but they often lack replacement rights meaning the right to rebuild or resume operations after a change in use, operational modification, vacancy, or casualty.
Consider this scenario:
A buyer acquires a distribution center operating as a legal non-conforming use. The tenant intends to modernize the facility with improved dock configurations, expanded trailer parking, and upgraded mechanical systems. Following closing, the tenant applies for building permits only to discover that even minor modifications trigger zoning compliance requirements. Suddenly, the municipality determines that the use is not permitted under current zoning and cannot be expanded or altered.
The consequences cascade quickly:
Operating restrictions may limit hours, truck intensity, or sub-uses essential for tenant viability.
Lender concerns emerge when the use cannot be legally confirmed, reducing collateral certainty.
Asset value falls sharply because future leasing is constrained by entitlement risk.
Insurance complications arise if the structure cannot be rebuilt in its current configuration following a casualty loss.
What initially appeared to be a straightforward acquisition becomes a distressed asset scenario—all because the underlying zoning status was not fully vetted prior to closing.
Truck Circulation and Access Requirements: Geometry Meets Regulation
A second area where zoning problems routinely surface involves truck circulation and access standards. Municipalities increasingly impose turning-radius standards, access spacing from intersections, and designated truck routes. These requirements can render an otherwise attractive industrial property functionally obsolete, especially for modern logistics tenants who rely on high-volume, fast-turnaround truck activity.
Scenario to consider
Imagine a cross-dock facility on a site constrained by public roads and adjacent development. During due diligence, everything appears operationally sound—ample pavement, multiple ingress points, and a history of industrial use. But a zoning compliance review uncovers that the existing truck entrances fail to meet current spacing requirements from the nearest intersection. Under today’s code, the site would be required to relocate its primary truck access point dozens or even hundreds of feet, an impossible reconfiguration given the surrounding built environment.
The fallout can be substantial:
Loss of truck access may render the facility unusable for Class A logistics operations.
Retrofits if even feasible, can require costly easements, road widening, or signalization improvements.
Municipal approvals may trigger a formal site-plan amendment, reopening issues such as screening, landscaping, and parking requirements.
Tenant agreements tied to throughput capability may be breached, exposing ownership to claims or vacancy risk.
Truck-related zoning issues often hide in plain sight. Without a dedicated zoning expert, buyers may not recognize that minor-seeming dimensional standards or access regulations can completely undermine the operational viability of the facility.
Why Experienced Zoning Providers Are Essential
“Zoning diligence for industrial assets isn’t a box-checking exercise,” Hall noted. “It’s about understanding how real-world operations intersect with codes that were often written for a very different era of industrial use.”
Experienced zoning analysts know where problems typically hide: sub-use restrictions, outdoor storage limitations, overlay districts, parking ratios, and unverified Certificates of Occupancy, to name just a few. They also understand how jurisdictions apply their codes in practice, which can be as important as what the code says on paper.
Goner noted that experienced zoning providers play a critical role in identifying and managing these risks early in the transaction process. At Palisades Property Trust, that work is handled through LightBox’s PZR zoning due diligence platform.
“PZR is best in class at clearly characterizing complex zoning issues,” Groner said. “That clarity allows us to sidestep pitfalls early in the process and move forward with confidence, even when a site presents regulatory challenges.”
In a capital environment where speed matters and entitlement risk is difficult to price, the cost of overlooking zoning issues far outweighs the investment in a thorough review. Industrial investors, developers, lenders, and corporate occupiers have learned that the most profitable deals are often the ones with the fewest surprises—and zoning-related surprises are among the costliest.
article continues after advertisement
Zoning Due Diligence Protects Industrial Asset Value
As industrial and logistics facilities evolve to meet modern supply-chain demands, zoning risk is rising in parallel. A property may appear to be an ideal acquisition target, but without expert zoning due diligence, buyers cannot be confident they can legally operate, expand, or re-lease the asset.
The message for the market is clear: zoning is no longer a procedural step in diligence. It is a strategic discipline that protects value, enables operations, and determines whether industrial assets can adapt over time.
Alan Hall, Senior Account Executive at LightBox PZR.
Alan Brings over 20 years of commercial due diligence experience and a wealth of experience in sales leadership roles in the commercial real estate industry. Alan led national sales for Old Republic Commercial Due Diligence Services, a nationwide provider of all third-party Due Diligence Services. Prior to that he managed the central U.S. as a Qualified Intermediary for OREXCO 1031, Old Republic National Title’s IRC § 1031 Exchange company.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/logistics.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-14 10:03:292026-07-14 10:04:48Why Zoning Due Diligence is Mission-Critical for Industrial and Logistics Properties
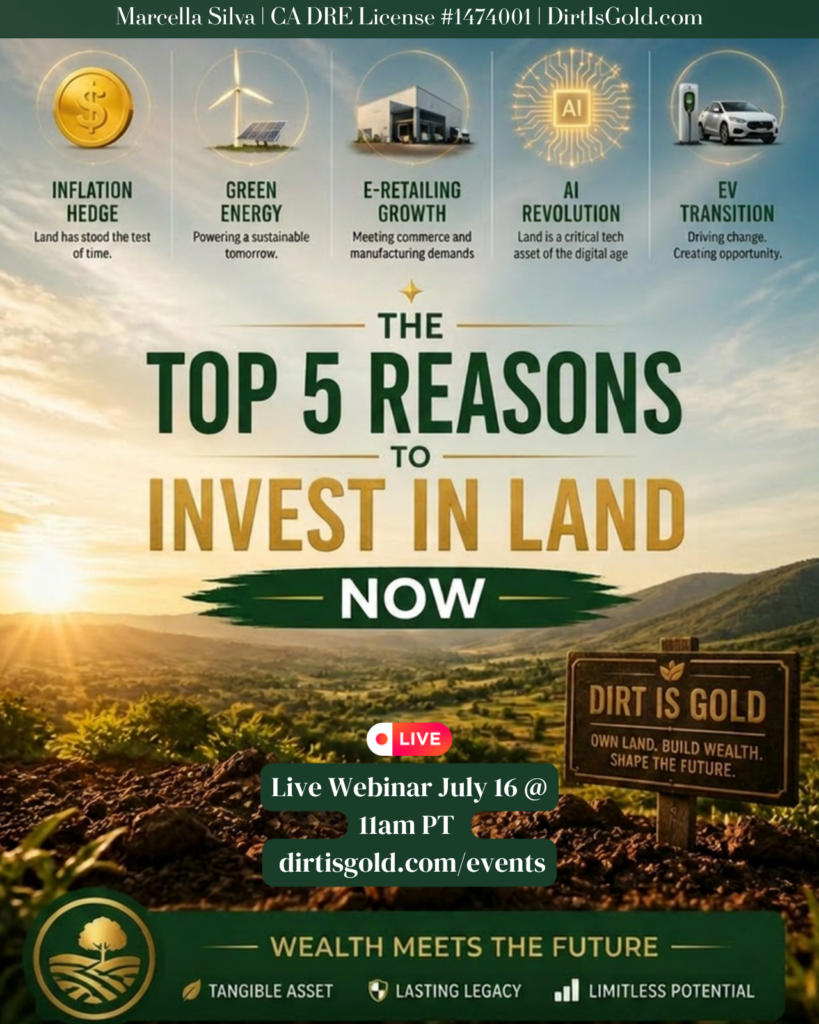
My friend and trusted land banking expert, Marcella Silva, is putting together an informational webinar on the one investment that never goes out of style — and I’d love for you to be there.
It’s called “The Basis of All Wealth,” and I’m hosting it on July 16th at 11am Pacific.
Here’s why I think this matters right now:
Most portfolios today are built on things that only exist as numbers on a screen. Stocks. Apps. Crypto. They can crash overnight, get hacked, or simply disappear.
But land?
Land is the ultimate “un-hackable” asset. Everything — every building, every road, every community, every data center — needs it. And they aren’t making any more of it.
In this session, we’re going back to basics:
• Why land is the ultimate inflation-proof asset
• How to position yourself in the path of tremendous growth where you own the asset everyone needs
• Why strategic land banking means owning a real asset that has No Tenants, No Toilets, and No Termites
• How investors are using Self-Directed IRAs and 1031 Exchanges to make their money work even harder
Since 2007, Realty411.com has assisted top companies expand their visibility and grow their business. Contact us for a complimentary marketing session: CLICK HERE.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/plant-gold.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-14 05:25:142026-07-16 04:44:33The One Investment That Can’t Be Hacked, Deleted, or Bankrupted 🔒
For busy professionals and parents managing bills, savings, and big family decisions, the hardest financial success challenges often start long before a spreadsheet. Negative money beliefs like “I’m just not good with money,” “more income will fix everything,” or “saving means missing out” can steer everyday choices off course and quietly undermine long-term financial goals. When those stories run the show, even solid plans get replaced by avoidance, quick comfort spending, or perfectionism that stalls action. A money mindset transformation begins by recognizing these patterns clearly and consistently.
article continues after advertisement
Understanding Money Biases and Beliefs
Your money mindset is shaped by two forces working together: cognitive biases and emotional money beliefs. Biases like immediate gratification, overconfidence, loss aversion, and reacting too strongly to headlines can steer choices even when you “know better.” One clue is how common overconfidence is, since as many as 80% of drivers consider themselves to be above average.
This matters because you can’t out-budget a brain that keeps rewriting the rules under stress. When you spot the pattern in real time, you can pause, choose a smaller next step, and stay consistent.
Imagine a bonus arrives and you plan to save it. A sale triggers instant reward, news sparks panic, and a recent loss makes “playing it safe” feel urgent, so the plan disappears. With this foundation, career moves can become a practical lever for lasting financial confidence.
Use a Career Reset to Raise Income and Rebuild Confidence
Once you’ve named the beliefs and biases shaping your money decisions, you can choose a change that proves a new story about what you’re capable of. A job or career shift can be a powerful mindset reset because it forces you to match your income with your values and long-term goals, rather than staying in a role that quietly reinforces scarcity or self-doubt. When you map roles that better fit where you want to go, you start seeing earning power as something you can build, not something you’re simply “given.” That shift often brings more than a bigger paycheck: it rebuilds confidence, expands your sense of opportunity, and makes investing in yourself feel practical instead of indulgent.
Education can be part of that reset, especially when online degree programs make it easier to keep earning while you study full-time or manage family responsibilities. For example, an accredited online MBA can strengthen leadership, strategic planning, financial management, and data-driven decision-making, skills that translate across many business environments and can support a higher-earning path. With that career direction in view, the next step is to turn your new mindset into small, repeatable actions you can practice day by day.
Weekly Money-Confidence Rituals That Stick
These habits turn a fresh money mindset into repeatable proof you can trust yourself with finances. When you practice them daily or weekly, confidence grows from evidence, not willpower.
Two-Minute Money Self-Talk Scan ● What it is: Practice being aware of your self-talk when you feel money stress. ● How often: Daily ● Why it helps: You catch scarcity scripts before they drive impulsive choices.
Weekly “Win and Lesson” Money Log ● What it is: Write one win and one lesson from your money week. ● How often: Weekly ● Why it helps: It trains progress focus instead of perfectionism.
24-Hour Pause for Unplanned Buys ● What it is: Delay non-urgent purchases and add them to a wish list. ● How often: As needed ● Why it helps: It creates space for values based decisions.
Automatic “Pay-Yourself-First” Transfer ● What it is: Schedule a small transfer to savings right after payday. ● How often: Every payday ● Why it helps: Consistency builds identity as a saver.
Spending Guardrails You Can Repeat ● What it is: Use self-control strategies like cash limits for flexible categories. ● How often: Weekly ● Why it helps: Guardrails reduce decision fatigue and prevent drift.
Apply the Earn-More/Save-More Playbook This Month
Mindset shifts stick faster when you can point to real-world wins: a little more income, a little less waste, and a clear plan for what the difference is for. Use the steps below to create quick momentum without relying on willpower.
1. Run a 30-minute “money leak audit”: Pull the last 30 days of spending and highlight anything that didn’t support your real priorities, subscriptions, delivery, impulse buys, bank fees. Choose one leak to pause for 30 days and redirect that exact amount to a specific goal. This works because it turns “spending guilt” into a clean experiment, which pairs well with the weekly ritual of dropping shame and focusing on behavior you can repeat.
2. Build a one-page “default budget” you can follow on autopilot: Set three numbers: (1) bills you must pay, (2) a weekly spending limit for flexible categories, and (3) a minimum automatic transfer to savings or debt. Then simplify categories to 5–7 buckets so you can review in 10 minutes each week. Autopilot reduces decision fatigue, which helps you manage money emotions before they become “I blew it, so why try?” spirals.
3. Create a side-income sprint with a tiny offer and a deadline: Pick one skill you already use at work or home (writing, organizing, tutoring, basic design, handy tasks) and package it into a simple, fixed-scope offer you can deliver in 2–4 hours. Set a goal to land one paying client in 14 days by sending 10 tailored messages to your network and posting one clear “here’s what I do + price + availability” note. Small, fast wins build tolerance for discomfort, the same muscle you’re strengthening in your confidence rituals.
4. Ask for more at your main income source (without making it awkward): Draft a one-page “value recap” with 3–5 measurable outcomes you’ve delivered, then propose either a raise, additional hours, or a new responsibility with a pay bump. If a raise isn’t possible, ask for something concrete that still improves cash flow like a stipend, overtime access, or schedule changes that enable a side gig. Treat this as practice in replacing limiting beliefs with evidence: you’re not “bad with money,” you’re building earning power.
5. Set one financial goal and break it into milestones you can hit weekly: Choose a goal that matters this month, $500 starter emergency fund, $300 toward a trip, an extra debt payment, and convert it into 4 weekly targets and 2–3 “if-then” rules. A planning approach like breaking down larger goals keeps the goal from feeling vague or overwhelming, which reduces panic spending and makes progress visible.
6. Add a “shared scoreboard” check-in if money is a household topic: If you share bills or goals, agree on one shared view of accounts, balances, and targets, then do a 15-minute weekly review: what changed, what’s coming up, what one action will help. The stat that families tracking finances together report stronger goal follow-through is less about the tool and more about reducing misunderstandings and keeping priorities aligned.
Money Mindset Questions People Ask Most
Q: What does the “money mindset” actually change in my day-to-day finances? A: It changes the choices you make when you feel stressed, bored, or behind. A helpful mental state can make it easier to follow a plan you already know is smart. Start small by deciding one default rule, like “I wait 24 hours before nonessential purchases.”
Q: How do I shift my mindset if I’m living paycheck to paycheck? A: Focus on control, not perfection: one bill paid on time, one fee avoided, one small buffer built. Pick a tiny weekly target you can repeat, even if it is $5 saved or one call to negotiate a bill. Consistency builds confidence faster than big promises.
Q: Why do I feel like “I blew it” after one bad spending day? A: That all-or-nothing feeling is common and it is a cue to reset, not quit. Write a one-sentence recovery plan: “I pause extras for 3 days and transfer $10 to my goal.” Then treat the slip as data about triggers, not a character flaw.
Q: When should I prioritize debt payoff versus savings? A: Many people do best with both: a small emergency cushion plus steady debt payments. A starter buffer helps you avoid new debt when life happens. Choose one number for each, automate it, and adjust after two pay cycles.
article continues after advertisement
Build a Long-Term Financial Success Mindset With One Trackable Step
It’s easy to know what to do with money and still feel stuck because old stories, fear, or guilt keep steering the wheel. The way forward is a long-term financial success mindset built on reflection on money beliefs and practical application of mindset principles in daily choices. When that approach is practiced consistently, it becomes easier to sustain money mindset changes, recover faster from setbacks, and keep motivation for financial growth rooted in progress rather than perfection. Change the belief, then prove it with small actions repeated. Choose one step to take now and track it for 30 days with a simple weekly check-in. That steady rhythm builds resilience, stability, and more confident decision-making over time.
Beth Harris
As the founder of businesstipscenter.com, Beth Harris knows a thing or two about making smart business decisions. She founded her company with the goal of providing entrepreneurs with an all-access platform full of business resources and tips. Beth understands that every day brings new opportunities to make the best decisions possible for your business. That’s why she’s dedicated to making it happen.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/financial-freedom.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-13 04:39:272026-07-13 05:01:37Transform Your Money Mindset to Unlock Financial Freedom and Success
Another loan that stands out on my personal list of accomplishments was a non-recourse loan for an investor who owned a 32-unit apartment building in Los Angeles that he had purchased with his Solo 401(k) some years earlier. The property was worth about $4 million at that time, in 2011. He needed to refinance a non-recourse loan of approximately $1.4 million to cover his debt and loan expenses.
The issue at that time was that there weren’t many, if any, non-recourse commercial lenders for multifamily properties owned in a retirement account. One lender I knew who handled non-recourse multifamily property loans in general (for your average investor) was Chase Bank. I communicated my client’s situation to their loan origination department and was initially turned down because they said they didn’t issue these loans for properties held in a 401(k). The typical nature of a 401(k) means there are other employees who might be involved in the ownership, which makes it too complicated to issue a mortgage.
However, once they realized the ownership was through a Solo 401(k), they reconsidered the transaction. It took a good three months to get the loan approved through the bank’s legal department. I was told this was the first time Chase Bank had approved a multifamily loan for a Solo 401(k), and, as far as I know, they never approved another one.
On top of that, I got my client an interest rate of 4.5% for five years. My client called me almost five years later to thank me again for getting him that loan and told me he had paid it off. His building was free and clear and worth a lot more money! Chalk one up for the small investor, thanks to LRG’s persistence and resourcefulness!
article continues after advertisement
Moving on, finding business is always challenging. I listed my company with a number of IRA custodian firms as a broker for non-recourse loans, as previously mentioned, so I did get referrals from time to time that way. These loans tended to be small and usually were limited to one-to-four-unit properties. The previously described loan was the largest non-recourse loan I had ever done until 2025, when I completed one for a client who owned 45 homes in his IRA. Therefore, those loan types tended to be much smaller, typically in the $50,000 to $200,000 range. I was grateful that I developed this specialty. I was the only broker in the U.S. for a while doing them. It provided a good, steady income stream for the first seven or so years they were available before they became more common and were offered by as many as a half-dozen non-recourse lenders or specialty firms.
Throughout my two decades in commercial real estate financing, a difficult residential loan request has seemed to find me every once in a while. This has just been a pattern that I’ve embraced since it still falls squarely within the category of helping people solve their real estate financing challenges. Here’s one of those unique situations.
100% FINANCING FOR A RESIDENTIAL PURCHASE?
LRG had a client in 2012 who rented one unit of a duplex in San Francisco for eighteen years. The duplex was owned by the son of the woman who lived in the other unit. Over nearly two decades, this couple helped the older woman with many chores on numerous occasions. When the woman passed away, the young couple asked the son if they could buy the property.
The son lived in Japan and was sympathetic to the couple’s desire to own the property. The challenge was that the couple didn’t have any money for a down payment to purchase it. The son was so grateful to LRG’s clients for helping his mother all those years they lived there that he reduced the price of the property from one million dollars to six hundred thousand dollars.
LRG was able to engage a private lender who was willing to accept the owner’s reduced sales price of six hundred thousand dollars for the couple. The lender, in turn, provided a six-hundred-thousand-dollar loan to enable the clients to complete the purchase of the San Francisco duplex. This 100% financing arrangement is an extremely rare occurrence in the world of residential lending. It certainly wasn’t a loan that a bank would have approved. Hence, another unique problem solved by LRG!
article continues after advertisement
PACIFICA LAND LOAN
In 2013, I was referred a land loan by another commercial mortgage broker I knew from prior dealings. She had no interest in handling this type of loan. The client was one of two partners who owned valuable acreage in Pacifica, CA, just south of San Francisco. The property consisted of about sixty acres bordering Highway One on the east side of the road. This was a good thing since they wouldn’t have to deal with the Coastal Commission regarding its development.
Their plan was to develop fifteen one-acre lots on the highest part of the property overlooking the Pacific Ocean and build fifteen executive-style homes of approximately four thousand square feet each. The clients also planned to donate the remaining acreage to the Golden Gate National Recreation Area (GGNRA) and receive a substantial tax write-off.
The challenge was more than twofold. First, when the clients purchased the land, the sellers carried back a loan of approximately one million two hundred thousand dollars. The elderly sellers wanted to be repaid and divest themselves of this burden. They were threatening to foreclose. My clients had only a limited amount of time to obtain a new loan, or the sellers would take the property back and sell it.
Second, if that wasn’t enough of a challenge, the property was not fully entitled or permitted by the county for the construction of the executive homes.
This deal taught me how to finance land loans. I went on to finance several of them over the following decade, but finding financing for this project was quite an exercise in overcoming rejection and the negative attitudes many lenders had toward land loans in general. I was simply too stubborn to give up.
After working on the loan for two to three months, I came across another broker who knew a private lender I wasn’t aware of. That’s one thing about this business. There’s always another possible lender out there that you don’t know about or haven’t found yet, and it can turn out to be the right lender for the deal.
The lender my associate introduced turned out to provide the solution we needed. The client had also pursued several financing options on his own, to no avail, and they were running out of time. The situation had become desperate if they were going to pay off the sellers and keep the land for development.
The result was a loan with some very harsh terms: an interest rate of 15% and 8 points—5 points to the lender and 3 points to my company. The lender provided a loan of one million three hundred fifty thousand dollars. This paid off the sellers and helped cover all closing costs.
It was another hard-fought battle that ended successfully. It almost didn’t happen, but everything came together in the end. Once again, the personal satisfaction of helping my clients salvage this property was something that’s hard to put a price on, not to mention completing a very difficult loan transaction that no one else had been able to accomplish. We also earned a fair fee for the work we had done.
19 HOMES IN MILWAUKEE
Another unique situation found its way to my desk. The client who was referred to me owned nineteen houses in Milwaukee, Wisconsin. They were under the threat of foreclosure if he didn’t pay off the original sellers who had carried back the financing when he purchased the properties.
LRG obtained a $700,000 loan through a private lender in Georgia, which paid off the existing debt and the real estate taxes owed. Suffice it to say, LRG saved the day.
This was one of the few transactions in which the client couldn’t afford to pay LRG’s fee at the close of escrow. There wasn’t enough money to pay the two percentage points the client had agreed to pay at the outset when requesting the loan. The client was an honorable man. He was grateful for what LRG was able to accomplish for him and appreciated the diligence it took to secure the loan. He paid the fee over the course of one month after the close of escrow until it was paid in full.
As the reader can tell, these real estate transactions are unique and demand a great deal of persistence to find a solution. I can say from my many years of experience dealing with all types of specialized real estate transactions that, for every successful escrow closing, there are ten or more deals that don’t make it. Not only do those disappointing deals fail to reach the funding stage, but they’re also wrought with frustrations and disappointments too numerous to count.
At the end of the day, all we can do is be satisfied with the home runs we hit, not the strikeouts we experience. The strikeouts, hopefully, make you stronger and more adept at succeeding in what you do and how you do it.
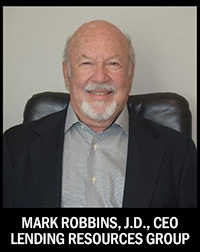
Meet Mark Robbins
Mark Robbins has pioneered non-recourse financing for IRA investors since leveraged financing became available to the public through a small bank in the Midwest in 2004. Since that time only a few select banks even offer these loans. He has established and maintained relationships with these lenders over the past twenty years.
Mark has obtained non-recourse loans, per IRS regulations, for numerous real estate investors in more than 30 states including Hawaii. Mark is a preferred provider for many of the IRA servicing companies including the Equity Trust Company, uDirect IRA, the Provident Trust Group, Entrust and many other IRA custodial and administrative providers for clients who require non-recourse financing for their IRA funded real estate investments.
Mark graduated from New York University in Bronx, New York with a B.A. in History and Western State College of Law in Fullerton, California with a Juris Doctorate (J.D.). Mark is an entrepreneur and has operated several different businesses over the past forty years including a division of a major commodities investment firm, his own hi-tech executive search company and presently a commercial real estate mortgage brokerage company known as Lending Resources Group Inc. that he founded in 2007.
He has been a real estate investor and developer having designed and built four homes since 1982. He became a mortgage banker in 2002 with Bank of America and went on to work for CTX Mortgage, a division of the home building company, Centex Corp., in Dallas. Mark was recruited to start an in-house mortgage division for a popular townhome development company in San Francisco in 2006. That firm dissolved in the wake of the financial crisis in 2007=2008. During his tenure in mortgage banking, Mark has generated more than $120 million in residential and commercial mortgages for homeowners and investors nationwide.
If you have any questions about how to invest your IRA in real estate, please contact Mark at 415-309-1803 or by email: [email protected]. You can also reference his website at: www.lendingresourcesgroup.com.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/diary.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-11 03:19:562026-07-11 03:22:03MARK…. MY WORDS – A PRIVATE MONEY MORTGAGE BROKER’S DIARY OF DIFFICULT DEALS (Part 2)
For mid-career professionals and busy parents weighing relocating near family, the pull is real: stronger support networks, easier childcare, and a steadier work-life balance. The tension is just as real, because changing zip codes can also change family dynamics, expectations, and the space that maintaining personal independence requires. The emotional challenges of moving often show up as guilt, pressure to be available, or worry about losing momentum in work and friendships. With the right approach, it’s possible to stay close, stay capable, and stay in charge of daily life.
article continues after advertisement
Plan Your Move Near Family Without Losing Autonomy
This process helps you move closer to family while keeping your routines, privacy, and decision-making intact. It matters because proximity can bring real support, but only if expectations are clear and your day-to-day life still works for you.
Define your “independence needs” in writing Start with a short list of non-negotiables like alone time, work hours, financial boundaries, and how often you want visits. Add your support goals too, such as occasional childcare help or shared dinners. Writing this down turns vague worries into clear requirements you can act on.
Choose a neighborhood based on friction, not just distance Pick an area that keeps your daily life easy: commute time, school or daycare options, errands, and access to your own friends and activities. Aim for “close enough to help, far enough to breathe” by considering travel time and traffic at the hours you will actually visit. This protects independence because convenience affects how often people drop in.
Compare housing options with boundaries built in Review layouts and setups that naturally support privacy, like separate entrances, a guest room with a door, or enough space for remote work. If you are considering living very close or on the same property, confirm how you will handle keys, parking, and quiet hours. The right home reduces daily negotiation and prevents small issues from becoming ongoing tension.
Set expectations early using simple, repeatable scripts Have one calm conversation before you move and cover three topics: how often you will see each other, what help you can and cannot provide, and how you will handle last-minute requests. Use clear language like, “We love being nearby, and we will usually plan visits 2 to 3 days ahead.” Consistent wording lowers guilt and keeps discussions from becoming personal.
Create a 30-day trial plan and adjust together Agree on a light first-month routine: one or two standing touchpoints, an emergency definition, and one protected family-free block each week. At the end of the month, review what felt supportive versus draining, then tighten or loosen the plan. A short trial period makes it easier to change course without drama.
Turn the Move Into a Career Reset With Research-Backed Insight
Once you’ve set up the logistics and boundaries that protect your autonomy, you can use the move itself as a clean break to realign work with the life you want near family. Changing careers during relocation can be a genuine reset: it’s a chance to choose roles that better match your personal priorities while still supporting flexibility, growth, and independence. That matters because many adults are navigating real constraints, caregiving demands, limited local options, and the simple fact that where you live can narrow what’s realistic.
At the same time, studies suggest that as burnout and dissatisfaction rise, many employers are leaning more on external hiring instead of developing the talent they already have, widening skills gaps and reducing growth opportunities for both workers and organizations. In that environment, your best path forward is often the one you intentionally map for yourself using evidence-based guidance about common barriers and how to work around them; resources like career help at University of Phoenix can help you ground a pivot in what adult workers typically face.
article continues after advertisement
Build a New Rhythm: Habits That Boost Life and Work
A move closer to family can be a powerful career reset and a personal reset, if you put a simple rhythm in place early. Use the habits below to protect your focus, grow your network, and stay grounded while everything is still in motion.
Design a “Week 1” work-from-home setup: Pick one spot as your default workspace, set a start/stop time, and run a quick test day before you commit to a full week. Write down your top three work requirements, quiet, calls, reliable internet, and solve those first so you’re not constantly improvising. If family is nearby, set an “office hours” boundary from day one (for example, no drop-ins during your core meeting block).
Use a transition schedule, not a perfect schedule: For the first 4–6 weeks, plan in “minimums” that keep life running: 3 priority work tasks per day, 2 admin blocks per week (mail, registrations, appointments), and 1 recovery block that’s non-negotiable. This supports the career pivot work you mapped earlier because it keeps your energy going to the skills and connections that matter, not to endless errands. If a day blows up, you still complete your minimums and move on without needing to “catch up” all weekend.
Choose one skill lane and learn in tiny reps: Re-read the career barriers you identified (time limits, location limits, caregiving demands) and pick one skill that directly reduces them, like a remote-friendly skill, a certification, or stronger communication habits. Commit to 20 minutes, three times a week, and keep a running “proof list” (projects, metrics, before/after examples) for your resume or portfolio. The fact that the professional development market size is valued at USD 56.89 billion is a good reminder that ongoing learning isn’t extra, it’s part of how people stay competitive.
Build local networking opportunities with a two-list plan: Create two lists: “career people” (your industry, hiring managers, peers) and “life people” (neighbors, hobby groups, parents, community members). Each week, aim for one coffee chat or meetup from either list, plus one follow-up message to someone you already met. Keep it low-pressure by using a simple ask: “I’m new to the area, what’s one organization or event that’s helped you meet good people?”
Join one community engagement commitment with a role: Pick a recurring activity that makes you useful, a committee, a volunteer shift, a class helper, because roles create repeat interactions and faster belonging. Research on sense of belonging connects it with well-being, and the practical takeaway is simple: show up consistently where people know your name. Start with a 60–90 day trial so you can quit guilt-free if it’s not a fit.
Set “closeness rules” before you need them: Decide what you can offer family (one dinner a week, a Saturday errand run, a standing call) and what you can’t (unplanned weekday visits, last-minute childcare during work hours). Put your default in writing, text is fine, so it feels like a shared plan, not a personal rejection. This keeps your independence intact and prevents small favors from quietly becoming a second job.
Real Questions About Moving Near Family
Q: How do I stay close to family without losing personal space? A: Choose distance on purpose: your own place if possible, or at least a private room and a “do not disturb” signal. Set visiting windows you can sustain, like one weekly meal plus a short weekend check-in. When you protect solitude early, closeness feels optional instead of consuming.
Q: What if my career takes a hit after the move? A: Keep your job story simple and forward-looking: you moved for family and you are building stability to do your best work. Update your LinkedIn location, schedule two networking chats per month, and pick one skill to build in small weekly reps. Momentum comes from consistency, not a perfect plan.
Q: How do I handle caregiving without it becoming my full-time job? A: Start with a caregiving menu: what you can do, what you cannot do, and what requires notice. The reality that 60% of family caregivers are employed is a reminder that boundaries are normal, not selfish. Ask the family to agree on backup options before a crisis hits.
Q: When should I talk about expectations with relatives? A: Do it before you arrive or during your first week, while everything still feels “new.” Use specifics like time blocks, holidays, money, and childcare so nobody relies on assumptions. Put the basics in a shared text thread so the plan is easy to revisit.
Q: How can I tell if I’m making the right choice when doubts pop up? A: Doubt is a data point, not a verdict, so write down what exactly you fear: loneliness, work disruption, or family pressure. Run a 90-day experiment with clear measures like income, stress, and relationship quality, then reassess. It also helps to remember moving for family-related reasons is the second most common motivation so you are not alone in weighing this.
Balancing Family Closeness With Independence, Work, and Long-Term Growth
Moving closer to family often brings a real tension: craving support and connection without losing personal space, work-life harmony, or the identity built where life is now. The steadier path is a positive mindset during change, paired with long-term adjustment strategies that protect boundaries while embracing family connections in a way that fits real life. When that approach leads, day-to-day decisions feel clearer, sustaining independence becomes normal, and ongoing personal and career growth stays in motion instead of on hold. Closeness works best when it’s chosen, bounded, and designed to support your whole life.
Gwen Payne
Gwen Payne is a stay-at-home mom with an entrepreneurial spirit. Over the years, she has mastered raising her two daughters while side hustling to success through small ventures based on her passions – from dog walking to writing to E- commerce. With Invisiblemoms.com, she hopes to show other stay-at-home parents how they can achieve their business-owning dreams.
https://www.realestateinvestormagazines.com/wp-content/uploads/2026/07/work-life-balance.jpg4001000dulcehttps://www.realestateinvestormagazines.com/wp-content/uploads/2013/04/logo.pngdulce2026-07-10 05:54:122026-07-10 05:54:23Finding Balance When Moving Near Family Without Losing Yourself